
Cledara AI Spend Report 2026 Reveals Anthropic and OpenAI Capturing 75% of UK AI-Native Spend
Cledara tracked anonymized payments from over 1,000 companies to reveal AI-native tools now represent 22.7% of total software spend, with Anthropic and OpenAI driving nearly all growth.
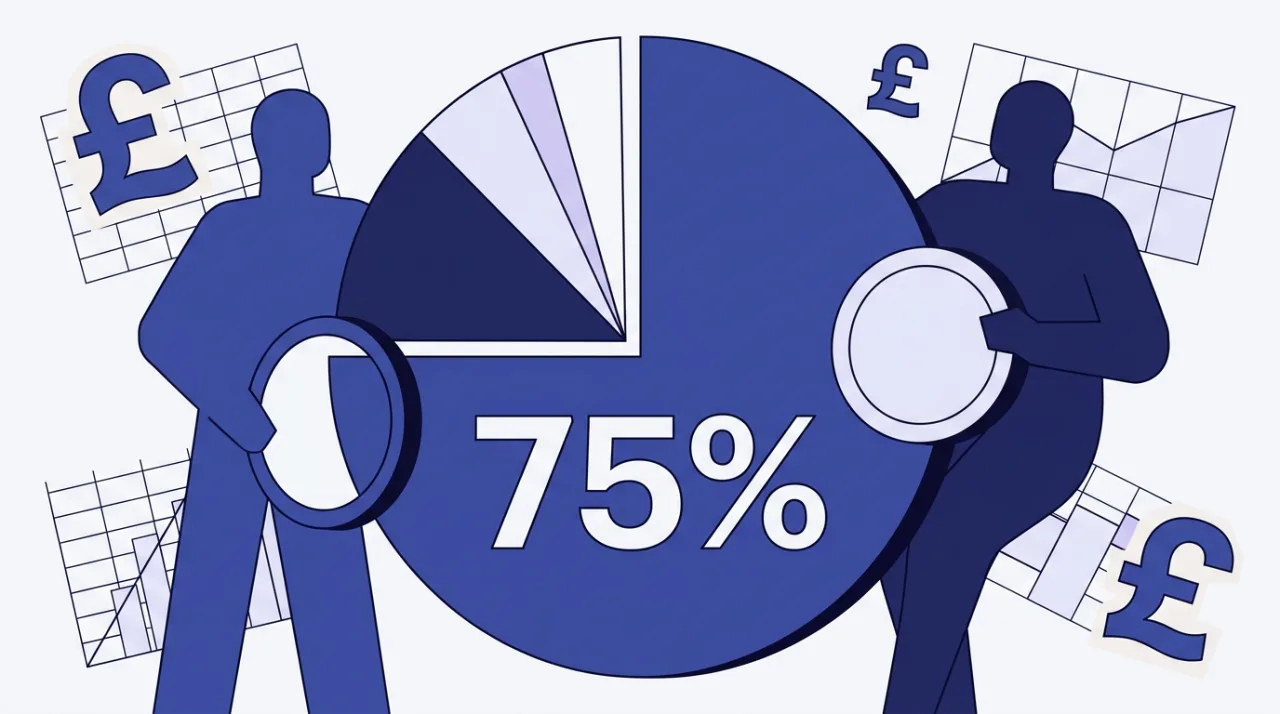
Cledara AI spend report 2026 data from August to October shows Anthropic and OpenAI together claiming 75% of UK AI-native spend, 73% in Europe and 67% in the US. The two providers increased their combined share of overall software spend to 14.0% by October, up 10.9 percentage points year-over-year. Growth came mainly from higher spend per existing customer rather than new sign-ups.
AI-native tools reached 27% of total software spend on the Cledara platform, up from roughly 3% two years earlier. October marked the strongest month in the UK sample, with AI-native tools hitting 22.7% of spend that month. The figures come from anonymized payments across more than 1,000 companies in 32 countries tracking nearly 9,692 tools.
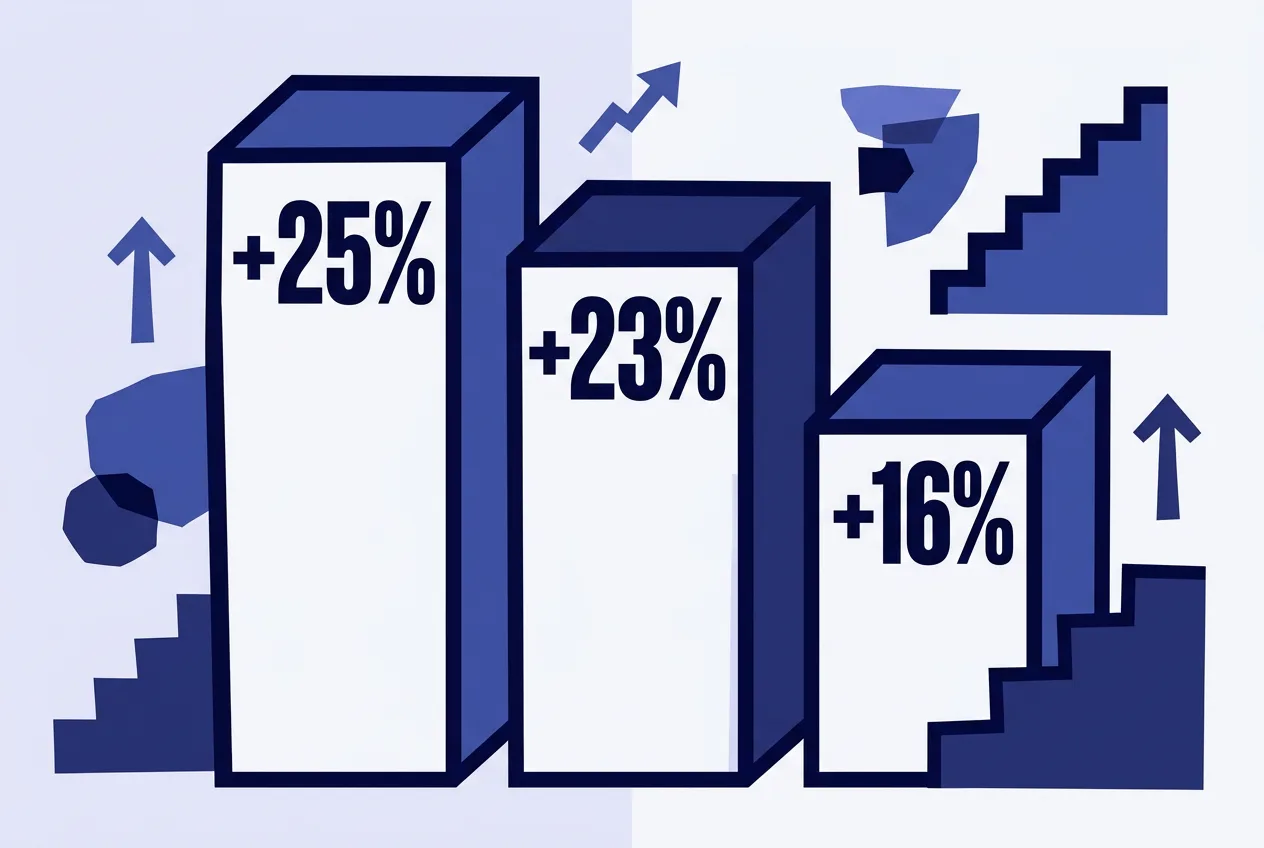
Regional AI-Native Spend Growth Rates
AI-native tool spend rose 25% in the UK, 23% in Europe and 16% in the US between the May-July and August-October periods when measured in local currencies. Usage-based pricing on tokens and APIs creates month-to-month volatility that differs from fixed SaaS subscriptions. Finance teams tracking these numbers now allocate budgets monthly for newer tools instead of locking into annual contracts.
Median companies in several regions now list AI Platforms & Model Ops among their top spending categories. Parallel industry benchmarks confirm rapid year-over-year growth in this category through October 2026. Teams that review overlap between tools reduce duplicate payments on coding and writing features now available inside frontier models.
Anthropic and OpenAI Market Share Trends
Anthropic recorded the largest gains: spend rose 41% in the UK, 38% in Europe and 19% in the US. Its share of AI-native spend reached 57% in the UK, 53% in Europe and 45% in the US. Claude ranked first overall by payment activity with a 12.35% share and first by spend with an 8.6% share in October data.
OpenAI spend grew 43% in the UK, 31% in Europe and 24% in the US. ChatGPT placed second by payment activity at 5.94% but fifth by spend at 4.4%. Roughly 88% of companies paying for Claude also maintain ChatGPT subscriptions. Average UK Anthropic payer spend reached £4,570 in October, reflecting higher per-company usage.
| Provider | UK AI-Native Share | Europe AI-Native Share | US AI-Native Share | Oct Spend Change |
|---|---|---|---|---|
| Anthropic | 57% | 53% | 45% | +19% to +41% |
| OpenAI | 18% | 20% | 22% | +24% to +43% |
| Combined | 75% | 73% | 67% | — |
Other Winners, Losers and Budget Steps
Smaller tools showing growth included OpenRouter with a 64% rise in paying companies, Granola with 58% Europe spend growth and Wispr Flow with 18% more companies. Grok gained companies from a small base. Many point tools lost ground because frontier models now include overlapping features.
Biggest declines hit Cursor with a 14% drop in paying companies and spend falls of 7-29% across regions, Perplexity with 23% fewer companies, Midjourney with 33% fewer and Otter.ai with 35% fewer. Finance teams reviewing these patterns now set monthly alerts and cancel tools that duplicate core model capabilities.
Practical steps include auditing coding and writing subscriptions for overlap, switching unproven tools to monthly billing and monitoring usage spikes before scaling budgets. Next Cledara edition is expected in early 2027; rapid share shifts mean teams should recheck concentration and ROI quarterly.
Frequently asked questions
How much of AI-native spend went to Anthropic and OpenAI in October 2026?
The two providers together captured 75% of UK AI-native spend, 73% in Europe and 67% in the US according to Cledara October figures.
Which tool showed the largest spend increase?
Anthropic recorded the biggest regional gains with spend rising 41% in the UK and 38% in Europe over the quarter.
What happened to point tools like Cursor and Midjourney?
Cursor lost 14% of paying companies while Midjourney lost 33%, reflecting consolidation toward frontier models with overlapping features.
How should teams adjust budgets based on the report?
Finance teams now favor monthly billing for newer tools, set usage alerts and cancel duplicate subscriptions before committing to annual plans.
Comments 3